An RCMP transfer to Winnipeg starts a clock. Under the RCMP Relocation Directive, most of your home-related benefits have to be used within a set window, and several only apply if you follow the steps in order. If you are being posted to Winnipeg (or leaving it), this guide walks through how the directive treats your home sale and purchase, what a good plan looks like, and where members tend to lose money on an RCMP transfer.
Important: the figures below come from the RCMP Relocation Directive published on rcmp.ca at the time of writing. Directives are amended, and your relocation coordinator decides what applies to your file. Treat this as a planning guide, then confirm every amount with them before you commit to anything.
Does your RCMP transfer qualify?
The directive applies to members transferred within Canada on an official transfer notice with a Crown-funded relocation. For a standard cost relocation, the distance between your old and new places of duty must be at least 40 km, and so must the distance from your old residence to the new place of duty. Expenses you incur before the RCMP transfer is authorized are not reimbursable, so hold off on listing your house or signing anything until your coordinator confirms the move is approved.
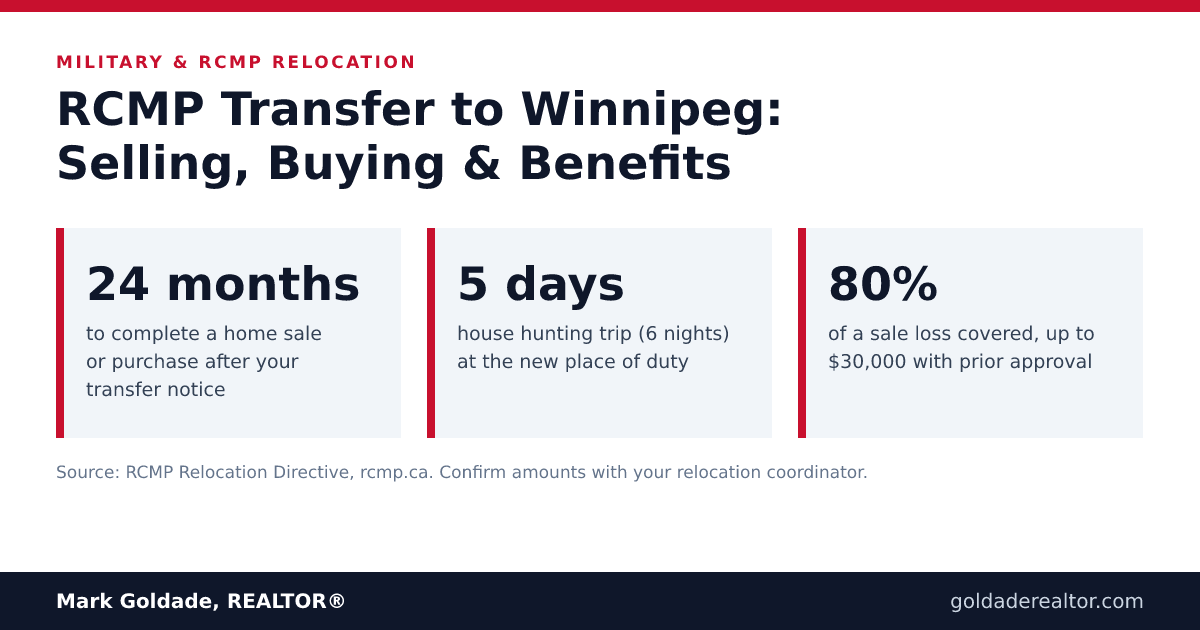
Most expenses must be incurred within 24 months of the transfer notice, and claims should be submitted within about three months of incurring them. Keep every receipt.
Core Account vs. Flexible Spending Account
Benefits come from two pools. The Core Account covers the basic entitlements. The Flexible Spending Account (FSA) funds optional extras up to a formula-based limit built from real estate commission (or rent), distance and household goods shipping. Unused FSA money is not paid out or moved to other benefits, so it is worth understanding what you plan to spend it on before you start.
Selling your current home
If you own a principal residence at your old posting, the Core Account can cover:
- One appraisal
- Real estate commission, up to the provincial ceiling rate
- Legal fees
- Mortgage early repayment penalty, equal to three months' interest and capped at $5,000
The sale has to complete within 24 months of the RCMP transfer notice. Lot size matters too: the directive limits eligible lots to 0.5 hectare, or 1.62 hectares where zoning requires it. If you own an acreage or a large rural lot, ask your coordinator early how the excess land affects your reimbursement. This is a common surprise for members selling outside a city.
Home equity assistance
If the home sells for less than you originally paid, the directive provides Home Equity Assistance of 80% of the loss, up to $30,000. It needs prior approval, and losses attributed to neglect of the property can reduce or deny the claim. Amounts above $15,000 may be taxable under CRA rules, so speak to a tax professional about your situation.
If you decide to keep the house
Members who retain the old home can qualify for a real estate incentive of 80% of the commission, to a maximum of $12,000. Whether keeping and renting makes sense is a separate question; our guide Posted Out of Winnipeg: Sell, Rent or Keep Your Home? covers it.
Buying in Winnipeg
For the purchase, the directive covers legal fees and disbursements (within provincial ceilings), structural and related inspections, and a mortgage interest differential of up to $5,000. Bridge loan interest is covered only for periods of 14 days or less, which is a good reason to line up your closing dates carefully. A lost deposit is reimbursed only when the RCMP cancels the transfer.
You also have to complete the purchase within the 24-month window. In practice, most members buy much sooner than that, so the bigger planning question is how to find the right home during a short trip.
Your house hunting trip
A House Hunting Trip is up to 5 days (6 nights) at the new place of duty, plus 2 days of travel. It is available if you have not already secured accommodation. Your own and your spouse's expenses come from the Core Account, while dependants are funded from the FSA. A second trip can be approved by the delegate in appropriate circumstances.
Members assigned Crown-Owned Housing receive a shorter Destination Home Inspection Trip instead.
To get the most from five days, do the groundwork before you land:
- Get your mortgage pre-approval first, so you can write an offer the same day you find the right home.
- Agree on a short list of neighbourhoods and your commute to your detachment or office.
- Have your REALTOR® send listings and a neighbourhood briefing before the trip, not after.
- Decide how you will handle your current home, since a sale and a purchase on different timelines can mean overlapping costs.
Interim lodging and getting settled
Interim lodging is available for up to 15 days from the Core Account (up to 15 more in exceptional cases with approval). Meals are paid at 100% for the first 10 days and 65% after that. Household goods coverage is up to 20,000 lbs from the Core Account, with up to 30 days of storage in transit. A Non-Accountable Relocation Allowance of $650 requires no receipts, and the transfer allowance equals one-twelfth of your gross annual salary.
What Winnipeg buyers should know
Winnipeg is one of Canada's more affordable big-city markets. The Winnipeg REALTORS® MLS® HPI composite benchmark price was $412,600 in October 2026, and it varies a great deal by area. Our guide to Winnipeg home prices by area shows how far apart neighbourhoods can be. Members posted to the city often compare in-city neighbourhoods with bedroom communities like Niverville, Lorette and Stonewall, which is covered in our rural price guide.
Mistakes that cost members money on an RCMP transfer
- Acting before authorization. Expenses incurred before your transfer is authorized are not reimbursable.
- Using providers the program will not reimburse. The directive limits service providers (appraisers, realtors, lawyers or notaries, and home inspectors) to a contracted directory with provincial ceiling rates, and they must be at arm's length from you. Confirm who qualifies before you hire.
- Missing the 24-month window on the sale or purchase.
- Slow claims. Submit within three months and keep receipts for almost everything.
- Assuming amounts are fixed. Always check the current directive and your coordinator's written approval.
Planning your RCMP transfer to Winnipeg
I work with CAF and RCMP members on both ends of a relocation. If you have an RCMP transfer notice for Winnipeg, get in touch before your house hunting trip so we can build your short list and timeline. You can also read more on the Military & RCMP Relocation page.
This article is general information, not legal, tax or financial advice. Source: RCMP Relocation Directive, rcmp.ca.
Related reading: Military and RCMP relocation services, Buying a home in Winnipeg, Principal residence exemption guide.